

The Australian government’s decision to scrap the 50% capital gains discount for all investments in the May budget came as a big shock for crypto owners. The new scheme effectively doubles the taxable component of a gain, minus a small discount for inflation.
But there are legal ways to minimize the amount of CGT you’ll have to pay — if you start prepping now.
Some Aussie crypto holders are taking drastic measures — like Finder founder and crypto king Fred Schebesta who is relocating to Singapore which offers 0% CGT, stating the tax changes were a “killer blow.”
But there are less dramatic methods to reduce your CGT bills including setting up a self managed super fund (SMSF), a company to trade crypto at the company tax rate, or to just cross your fingers and hope the opposition will reverse the changes after the next election.
Source: YahooFinance
What’s changing with CGT on July 1, 2027?
Since 1999, Aussie asset owners have only paid tax on half of their capital gain. From July 1, 2027 they’ll pay their full income tax rate — which means 30% CGT if your income and gains are between A$45,000 and $135,000, 37% for the portion between $135,000 and $190,000 and 47% above that. (All figures in this story are in Aussie dollars)
Adding insult to injury, low-income earners who aren’t on welfare like students and retirees will pay a minimum 30% CGT rate no matter how little the gain.
The only discount now available accounts for the effect of inflation on your cost basis. So if you buy a house for $1 million in 2027 and sell it for $1.5 million after 10 years, with inflation at 3%, you won’t have to pay tax on the $344,000 or so attributed to inflation.
“The challenge for cryptocurrency is that the CGT changes, indexation really helps slower growing assets not fast ones,” explains Andrea Yuen, Swyftx CEO.
So if you bought Bitcoin for $10,000 and sell it ten years later for $100,000, the inflation discount is only around $3,439. Under the old system you would pay tax on $45,000 of gains. Under the new system you’ll pay tax on $86,561 of gains.
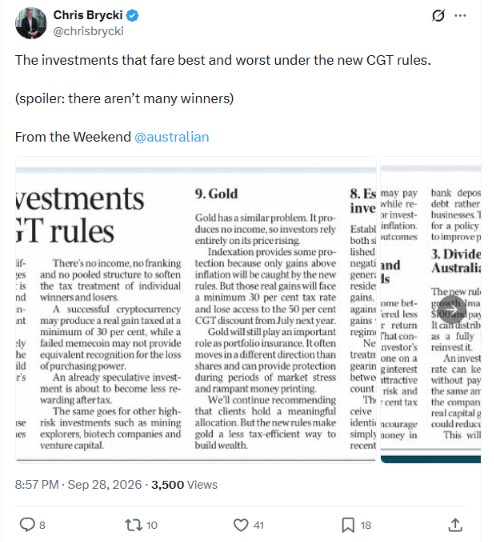
Stockspot analyst Chris Bryki compared how ten different asset classes would fare under the new rules.
“Crypto sits at the bottom because almost its entire return comes from capital growth,” he wrote in The Australian newspaper.
“An already speculative investment is about to become less rewarding after tax.”
Here are a few different strategies to help crypto holders deal with the changes, ranging from little to no effort, to restructuring your entire life.
1. Hope for a massive bull run before July
Any gain you’ve made before July 1 2027 will be taxed under the existing 50% discount scheme. So your best bet is to hope a raging bull market pushes the value of your portfolio as high as possible before that date.
You should faithfully record the value of every crypto asset you have that day, as any gain from that value will be taxed at the higher rate.
Ben Simpson, founder of crypto advisory service Collective Shift, says Bitcoin’s performance since mid-year in a challenging macro environment bodes well for further gains before July.
But Simpson (who points out he’s not a financial advisor) adds, “I probably wouldn’t be betting the farm on the fact that we’re gonna have a huge bull run”
“I think the halving in May 2028 is where we’ll see most of the returns. So I don’t think it’s going to work in investors’ favor.”
Yuen notes that prices aren’t within your control. “A strategy isn’t a strategy if you’re just sort of hoping,” she says.
2. Vote for a party that will reverse the CGT changes
Both the official opposition The Coalition, and the insurgent opposition One Nation, have promised to reverse the changes. Crypto voters who feel strongly enough about this single issue, could vote for a change in government.
However, the ruling ALP holds 94 out of 150 seats in the House of Representatives and will be difficult to dislodge from office. If the government does change — and the legislation can pass the Senate in time — it’s technically possible the changes could be reversed before anyone has to file taxes from July 1 2028.
But it’s probably more likely that any change to the system would occur after that date. Adrian Forza, director of Crypto Tax Australia, says this would make calculating gains very difficult.
“It would be a nightmare to do three calculations, but longer term, it’ll be better for the public.”
3. Shift your crypto into a self-managed superannuation fund
Australian retirement funds are called superannuation funds, and once you are over 60 you can access your investments tax-free — even as they keep growing.
Unfortunately none of the retail super funds allow clients to invest in crypto, so if you want to protect your crypto gains using this method, you’d have to set up an SMSF. About a third of Simpson’s high net worth clients invest in crypto via SMSFs.
“Buying Bitcoin and accumulating it there is a super solid idea,” he says, although he cautions against adding many altcoins. “You’re risking your retirement, which is an ultra long-term hold, on short-term altcoins,” he says.
Australian super fund AMP has invested in Bitcoin — but doesn’t allow its clients to do so.
The big drawback with SMSFs — explains the 27-year-old founder — is that younger crypto investors can’t access the money for decades.
“You can’t touch it until you’re in retirement, right? So you can’t really utilize any of those gains until later in life.”
Realistically then, it’s a strategy more suited to wealthier investors aged over 50, who have a shorter period to wait.
Related: Older investors are risking everything for a crypto-funded retirement
The government has also made running an SMSF a pain in the backside, with lots of compliance paperwork and audits, as well as a bunch of unavoidable fees that make it prohibitive for smaller balances.
Annual costs typically range between $2,000 and $4,000, although online providers like Stake can reduce total annual costs to around $1,330, as long as you only buy Bitcoin or Ether ETFs.
You also have to sell any crypto and pay tax on it before you can rebuy it with your SMSF, and there are annual contribution limits to factor in, although Forza says you should be able to get almost $400,000 in there with a bit of creativity.
Keep an eye out in December for a detailed report on how to set up a crypto SMSF.
4. Borrow against your Bitcoin to avoid a CGT event
A strategy some billionaires employ to avoid paying tax is by borrowing against their assets, as repaying the loan often works out cheaper than paying tax on a sale.
Bitcoiners can now access a range of lenders, including BlockEarner, Veild and Swyftx, that let you employ a similar strategy by borrowing against your BTC as collateral.
“We like to bring that strategy to the masses, not just to billionaires,” laughs Yuen.
But it can be risky if you don’t have a billionaire’s deep pockets. Borrowers face high interest rates, relatively short loan periods (typically 12 months), and risk losing their Bitcoin if the market moves against them. You can’t borrow against the full value either — Swyftx has a loan-to-value ratio around 40%.
”If your collateral drops below a certain amount, there will be a margin call,” she says. “I would say it’s a bet on a price going up. I think you have to have a view that crypto will go up — or at least not go down so that you get margin-called… Otherwise, a crypto-backed loan wouldn’t make sense for you.”
Simpson doesn’t recommend this strategy due to the risks, but says it can pay off for some people. For example if you borrow at 10% interest, and Bitcoin compounds by 33% a year (as it has done in the past) you’d end up much better off than paying CGT.
But he warns it’s a leveraged bet that is best suited to sophisticated investors.
“I wouldn’t recommend it for someone that’s highly exposed to crypto and doesn’t have the capital behind them because it’s a risky thing if you don’t know what you’re doing.”
Bitcoin is down 28% over the past year, so anyone borrowing a year ago would have faced margin calls and possible liquidation as well as interest costs.
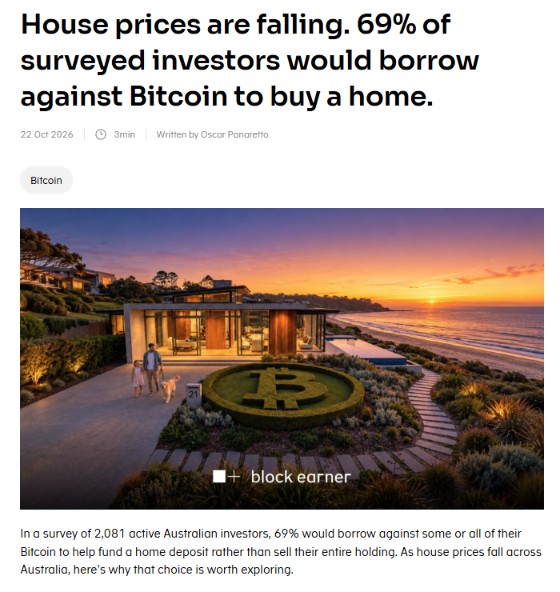
Borrowing against Bitcoin for a house deposit has become a more popular strategy. (BlockEarner)
Forza cautions that borrowing crypto can also be a CGT event in some circumstances, such as borrowing in DeFi. If you deposit ETH to Aave, it gets automatically swapped to WETH which is a taxable event, and when you withdraw the ETH it’s another taxable event.
Borrowing from centralized lenders like BlockEarner or Swyftx is currently a grey area, and the ATO has not clarified if it’s a taxable event.
”If you’re talking about [borrowing] ten grand fine. But if you’ve got three to five Bitcoin, I wouldn’t risk it because if it goes against you then you’re going to be paying tax.”
”Vield is the only one in Australia that’s got a private ruling that says their product is not a taxable event. No one else has got one.”
Swftxy confirmed it has not got a private ruling and said clients should seek tax advice, while BlockEarner did not respond to a request for comment.
In part two of our Aussie CGT special, coming later this week, we’ll bring you the final four strategies to minimize your crypto tax bills, including setting up a company or leaving the country entirely.
Also read: Baby boomers worth $79T are finally getting on board with Bitcoin
Read the full article here